

For as long as most of us have followed the oil market, one sentence has been treated as close to physical law: Saudi Arabia is the swing producer. When the market needed barrels, Riyadh opened the taps. When it had too many, Riyadh closed them. Every OPEC meeting, every ministerial statement, every rumor out of Vienna got read through that lens, because for the better part of five decades it was the correct lens.
I don’t think it’s the correct lens anymore, and the evidence for that has been piling up in plain sight for the last eighteen months. The market’s actual balancing mechanism has moved. It isn’t sitting in Riyadh. It’s sitting in Beijing, in the form of a state apparatus that has quietly become the largest discretionary buyer of crude the world has ever seen, and it is behaving exactly the way a swing producer would, just from the other side of the ledger.
This matters for anyone who owns oil, owns tankers, or is trying to figure out why the price of crude keeps refusing to do what a war in the Middle East says it should do.
What “Swing Producer” Used to Mean
The mechanics were simple. OPEC, led by Saudi Arabia, held spare capacity in reserve and used it to defend a price band. Too much oil, cut production. Too little, add it back. The 2014-16 episode and the 2020 Saudi-Russia price war were both, in their own way, proof the mechanism still worked: Riyadh chose to not play the role for a while, on purpose, and the market found out in a hurry what happens when nobody is holding the other end of the rope.
What’s changed isn’t that Saudi Arabia lost the physical capacity to swing. It’s that the marginal barrel setting the price is now more often a buying decision made in Beijing than a production decision made in Riyadh.
The Quiet Handoff: China’s 2025 Stockpiling
Through 2025, China stockpiled an estimated 0.9 to 1.0 million barrels a day of crude (Rystad Energy puts stockpiling at roughly 83% of that year’s entire import growth). This was not demand. Chinese refiners were not burning an extra million barrels a day. This was inventory management: taking advantage of a soft price environment to fill strategic and commercial storage that had sat comfortably below capacity for years.
That barrel never reached the tradeable global market. It went into a tank instead of into a ship’s discharge line, and the EIA has explicitly credited this stockpiling with supporting prices that would otherwise have fallen further. Functionally, China was doing what OPEC used to do when it cut production, removing barrels from the market to defend a price level, except it was doing it from the demand side, with a checkbook instead of a valve.
Nobody put out a press release about this. It happened quietly, month after month, in customs data most people don’t read.
The Mechanism Runs in Reverse
Then the Iran war closed the Strait of Hormuz, and the same mechanism ran backward.
Chinese seaborne crude imports fell to roughly 6 million barrels a day by June 2026, the lowest level since October 2016. Refinery run rates fell with them, particularly among the independent “teapot” refiners that had grown structurally dependent on discounted, sanctions-tolerant Iranian barrels. When that supply got cut off, a lot of that capacity simply stopped running rather than pay up for substitutes.
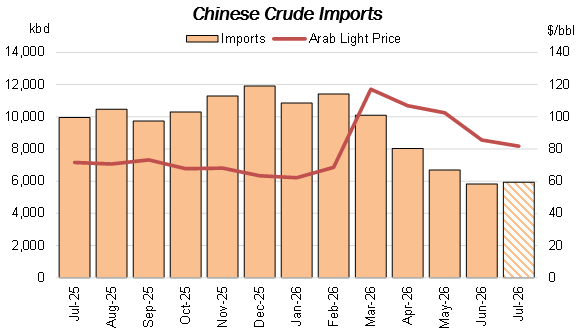
Here’s the part that should have gotten more attention than it did: China absorbing that shock by buying less is a meaningful part of the reason Brent never spiked to the level a full Hormuz closure should, on paper, have produced. A supply shock of that magnitude, hitting a market with normal demand elasticity, should have been genuinely ugly. It wasn’t, because the buyer on the other side pulled back exactly when the seller couldn’t deliver anyway.
China has now swung in both directions, filling up when crude was cheap, pulling back hard when it wasn’t, and the financial press has started calling it what it is. CNBC, Bloomberg, and Axios have all run pieces this year describing China as the oil market’s new swing importer. That’s not a cute turn of phrase. It’s a genuine description of who is now doing the job OPEC used to do.
OPEC’s Cohesion Is Cracking at the Same Time
The timing here is not a coincidence, and it’s not kind to OPEC’s credibility as an institution.
The UAE left OPEC entirely on May 1, 2026, to pursue production unconstrained by a quota system it had outgrown, its real capacity had drifted well above what its quota allowed for years. Iraq, OPEC’s second-largest producer, has quietly floated its own exit unless its quota, currently 4.378 million barrels a day, gets raised toward the production it says its capacity now supports. Whether or not Iraq actually walks, the fact that it’s a live conversation tells you something about how much internal discipline is left in the room.
An organization built to act as a single, coordinated swing producer doesn’t work if its second-largest member is threatening to leave over a quota dispute and its most operationally flexible member already has.
Riyadh’s Answer: The Biggest OSP Cut Since 2000
Against that backdrop, Saudi Arabia’s August Arab Light OSP to Asia landed like a statement. Aramco cut the price by $11 a barrel, the largest monthly reduction since at least 2000, pushing Arab Light to a discount against the Oman/Dubai benchmark for the first time since the 2020 price war, and to its lowest absolute level since June 2020.
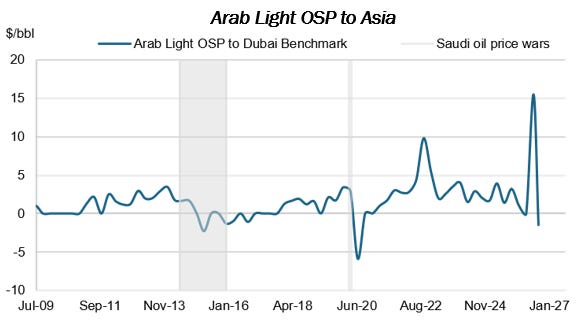
You can read that as a purely mechanical response to soft Asian demand. I don’t think that’s the whole story. A cut of that size, delivered in one move, reads less like a price-taker adjusting to conditions and more like a price-setter defending share against a buyer, China, that has just demonstrated it has real leverage and isn’t afraid to use it. Whether this is the opening move of a deliberate price war or simply market-share defense that happens to look like one, it’s one more data point in the same direction: the cohesion that let OPEC act as a single swing producer for decades is coming apart at precisely the moment its actual balancing function has moved to Beijing.
The Setup
If August’s OSP cut is the opening move of something bigger rather than a one-off, the historical playbook says to expect Saudi Arabia, and now potentially the UAE and Iraq, both operating outside OPEC’s quota discipline, to add barrels rather than withhold them. That’s incremental ton-mile demand for VLCC and Suezmax tonnage on Middle East-origin routes, regardless of what price those barrels ultimately fetch.
The genuinely open question is where those barrels land. China’s own appetite is the least certain variable in this cycle, given an already-full 2025 stockpile and softening teapot-refinery runs. If Beijing stays on the sidelines, the incremental barrels have to find buyers elsewhere in Asia or Europe, which reshuffles trade routes and haul lengths more than it changes the aggregate ton-mile total. If China re-engages instead, the Middle East-to-China VLCC route (still the single largest crude trade in the world by volume) is where any rally would show up first, and a full return to China’s pre-war import run-rate of roughly 11.5-11.8 million barrels a day, nearly double the current level, would be unambiguously bullish for the entire crude tanker complex.
This comes at a time when oil-on-water, i.e. crude loaded on tankers, is at seasonal highs, which means tanker utilization is already high.
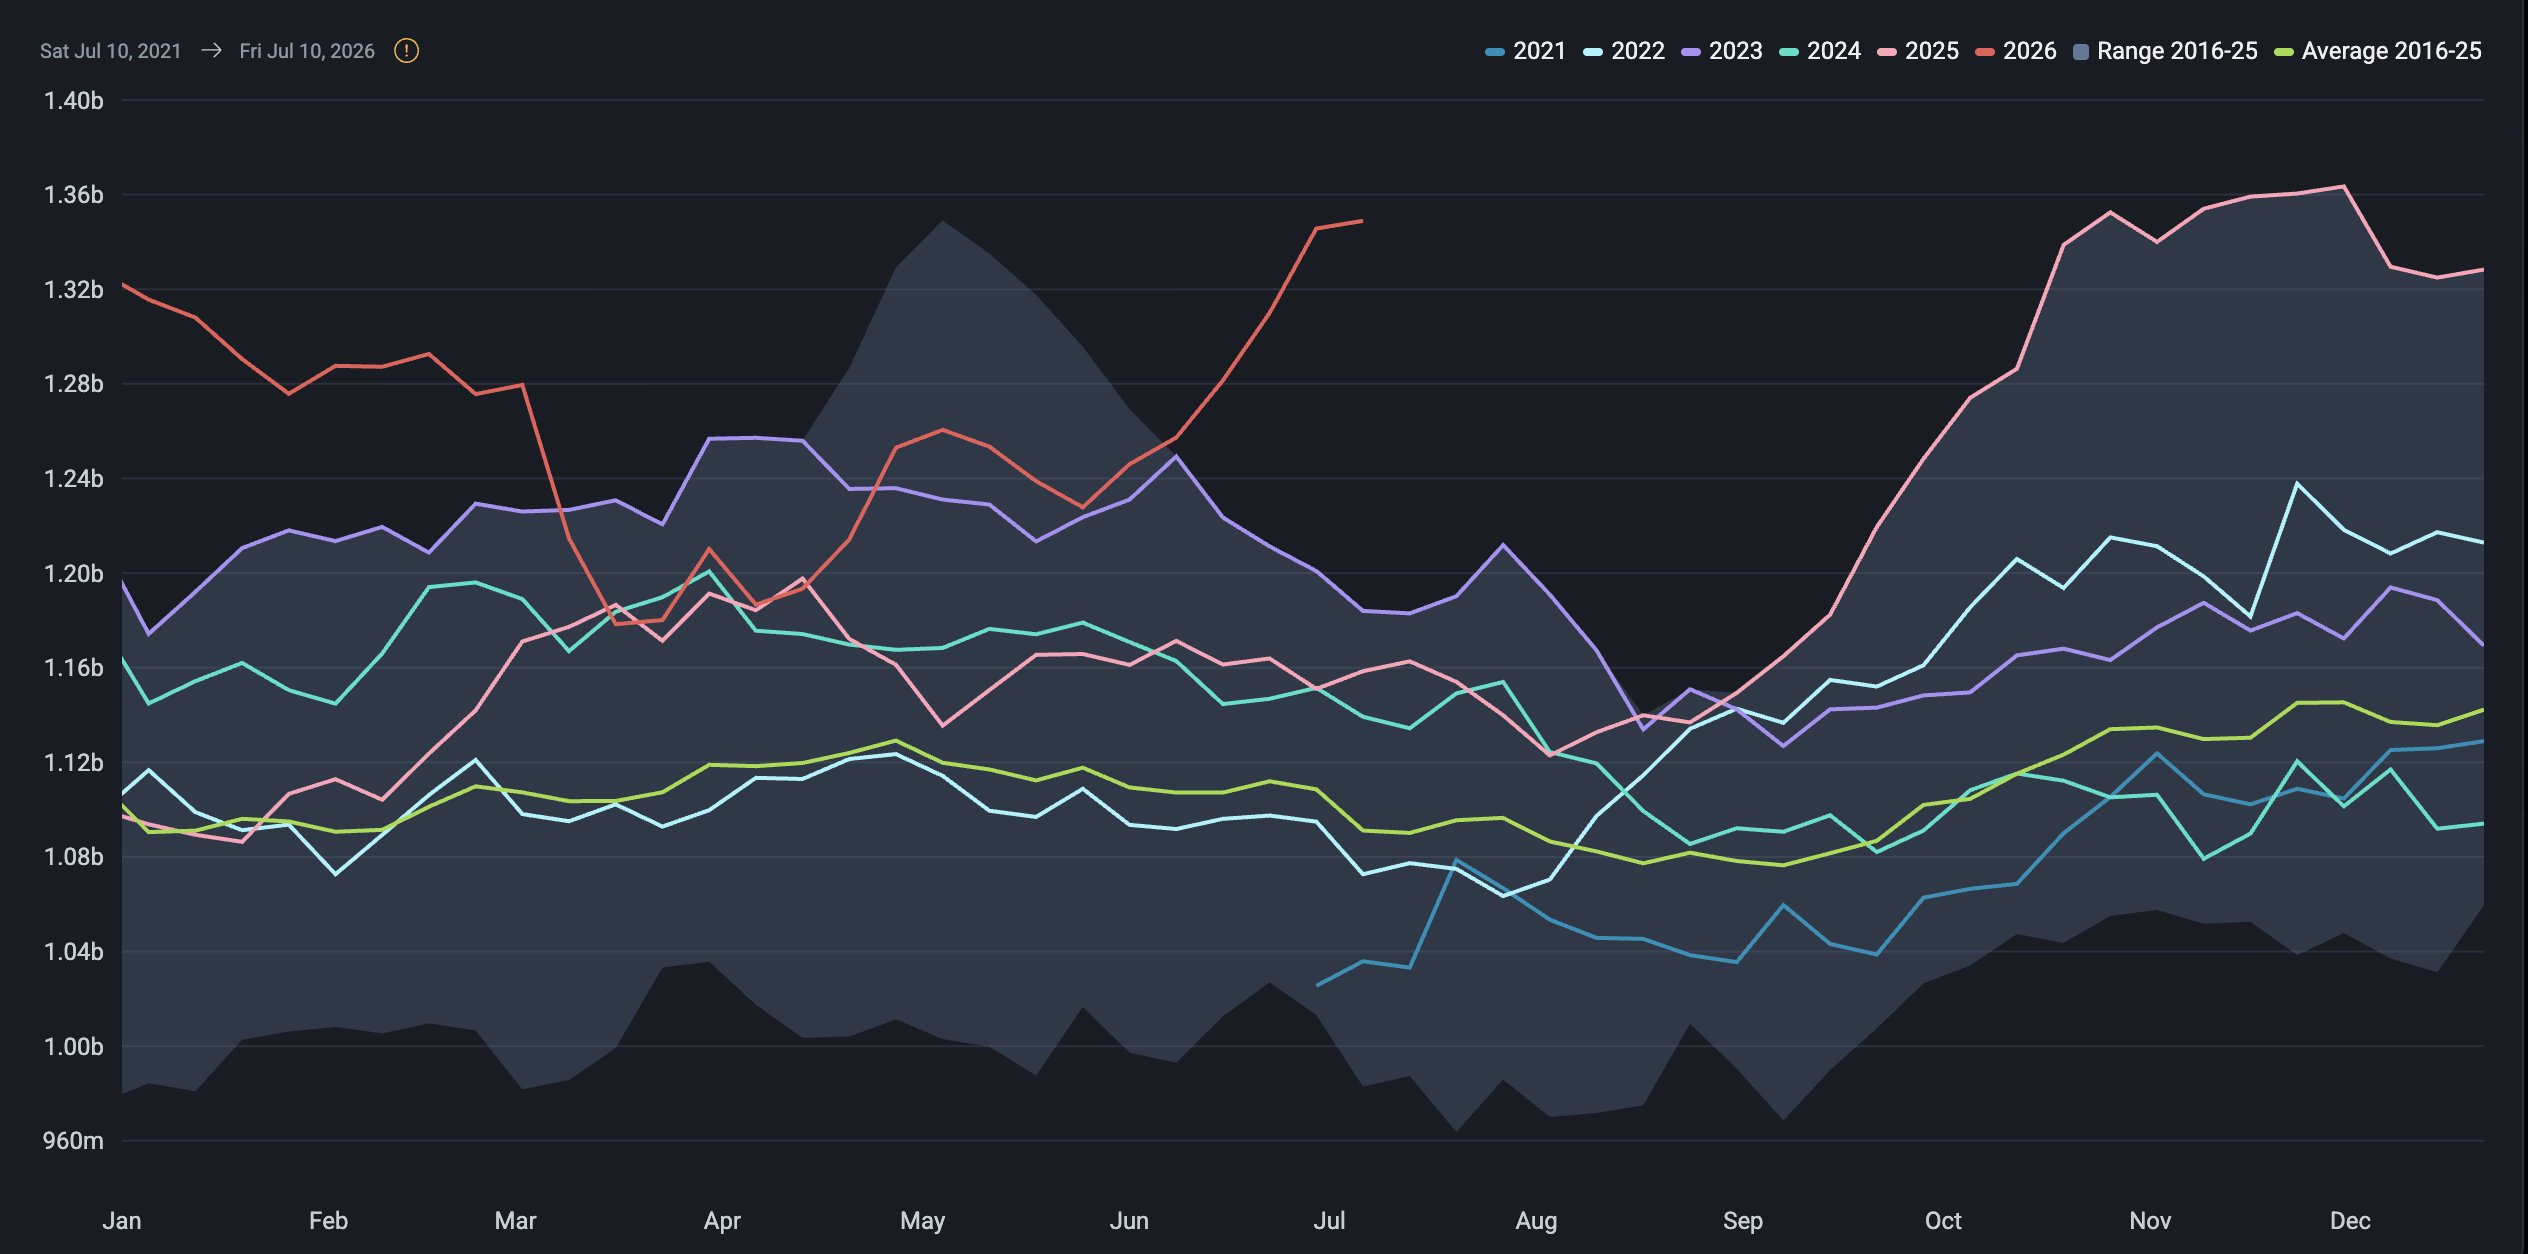
Either way, the framework that mattered for the last forty years — watch what Riyadh does, is no longer sufficient on its own. Watch what Beijing buys.
This is not investment advice. Do your own work.
Thrilled Ayuso has a free (just unheard of today..) outstanding analysis available to us all. Thank you so much!!
I am not religious, but your substack being free is as close to a gift from God as I've seen.